"At Vidhu Duggal & Company (VDC), we assist entrepreneurs, investors and established businesses with company formation in Dubai. Our support covers jurisdiction selection, business licensing, legal structures, documentation, tax registration and ongoing compliance in the UAE and India."
Setting up a company in Dubai can open up opportunities to work with customers across the Middle East, Africa, Europe and Asia. The city has a well-developed business environment, international banking facilities, modern infrastructure and access to a diverse talent pool. It is also a popular choice for Indian entrepreneurs looking to expand beyond the domestic market.
However, registering a company in Dubai involves more than selecting a trade name and obtaining a licence. The choice between Mainland, Free Zone and Offshore registration affects where the company can operate, the activities it can undertake, its visa eligibility and its tax obligations.
Indian residents also need to consider the rules governing overseas investment (ODI/FEMA) and the tax treatment of foreign income and assets in India (POEM, DTAA, and Schedule FA).
Free Consultation
Dubai is an established business centre for companies that want to serve international markets. Its location, transport links and business infrastructure make it practical for businesses dealing with customers and suppliers across different countries.
For Indian entrepreneurs, Dubai can also provide a convenient base for managing international operations while maintaining commercial relationships with India.
Some reasons businesses consider Dubai include:
Dubai has strong air, sea and road connectivity with major markets in the Middle East, Africa, Europe and Asia. Businesses involved in trading, logistics, consulting and technology can use this network to manage cross-border operations.
Foreign investors can hold 100% ownership in many UAE Mainland business activities and in Free Zone entities. The applicable ownership conditions depend on the activity, legal structure and licensing authority.
Dubai offers commercial offices, logistics facilities, technology hubs, co-working spaces and specialised business zones. Companies can choose facilities based on their operational requirements and budget.
The UAE has introduced a federal Corporate Tax system, but its rates and rules remain relevant when comparing international business locations. Qualifying Free Zone entities may benefit from a 0% rate on qualifying income if they meet the prescribed conditions. This benefit is not automatic for every Free Zone company.
An Indian company looking to serve overseas clients may consider Dubai as a regional operating base. It can also be relevant for Indian founders entering international markets, establishing a trading presence or building relationships with overseas investors.
Businesses generally consider three broad routes for company formation in Dubai: Mainland, Free Zone and Offshore registration. Each has a different purpose and set of restrictions.
A Mainland company is licensed by the relevant UAE authority. In Dubai, the Department of Economy and Tourism (DET) is the main licensing authority for many business activities.
A Mainland licence is generally suitable for businesses that want to operate directly in the UAE market, work with local customers or undertake activities that require a Mainland presence. Many activities allow 100% foreign ownership. However, certain strategic or regulated activities may have additional ownership, approval or licensing conditions.
A Free Zone company is registered with a particular Free Zone authority. Dubai has several Free Zones, including DMCC, IFZA, Meydan and DAFZA.
Free Zones are popular with international entrepreneurs because they offer full foreign ownership, different office packages and licensing options for specific business activities. A Free Zone company can generally operate within its permitted zone and conduct international business. However, selling goods or providing services directly in the UAE Mainland may require a distributor, a Mainland branch, a permit or another approved arrangement.
An Offshore company is generally used for holding assets, owning shares in other companies and certain international investment or wealth-structuring purposes.
It is not designed as a regular operating business with unrestricted access to the UAE domestic market. Offshore entities usually cannot conduct normal commercial operations in the UAE Mainland and generally do not provide the usual route to UAE residence visas. Bank account opening is subject to the bank's independent due diligence; incorporation does not guarantee an account.
A Mainland company is worth considering if your business needs to work directly with customers across the UAE. Depending on the activity and licence, a Mainland entity may be able to operate from approved commercial premises, enter into local contracts and participate in government or private-sector projects.
Many commercial and industrial activities permit 100% foreign ownership. However, ownership conditions should be checked against the exact business activity before incorporation.
Some activities require approvals from additional authorities. Regulated sectors such as healthcare, education, financial services, transport and certain professional services may have their own licensing requirements. The business activity also determines the type of licence, approvals, office requirements and qualifications needed.
A Mainland structure may be appropriate for:
The final structure should be selected after checking the activity, ownership rules and operating requirements.
Free Zones are designed to attract international businesses and investors. They provide a separate regulatory framework, with each authority setting its own incorporation, licensing and workspace requirements.
Popular options include DMCC, IFZA, Meydan and DAFZA. The right choice depends on the business activity, customer base, expected transaction volume, office needs and budget.
A Free Zone licence does not give a company unrestricted permission to carry out every activity in the UAE Mainland.
A company planning to sell goods or provide services directly to Mainland customers must check the rules applicable to its activity. It may need to work through an authorised distributor, obtain a relevant permit or establish a Mainland branch or entity. This point should be considered before selecting a Free Zone only because its initial licence package appears less expensive.
A Free Zone company is not automatically exempt from UAE Corporate Tax.
A Free Zone entity that meets the conditions to qualify as a Qualifying Free Zone Person (QFZP) may benefit from a 0% Corporate Tax rate on qualifying income. The conditions include:
Income that does not qualify may be taxed at the applicable standard rate (9%). Businesses should review their activities and revenue streams before assuming that the 0% rate will apply.
Offshore companies are generally used for international holding and investment structures rather than day-to-day trading operations within the UAE.
Depending on the registry and applicable rules, an offshore company may be used to:
An offshore company is not the same as a Mainland or Free Zone operating company.
It generally cannot carry out normal commercial activities within the UAE Mainland. It also does not usually provide the standard investor or employee visa facilities available through operating companies.
Banks may request detailed information about the company's ownership, source of funds, business purpose and expected transactions. An offshore registration certificate alone does not guarantee banking facilities. Offshore registration is therefore more suitable when the purpose is holding or investment rather than establishing a local operating presence.
The following comparison gives a broad overview. Actual conditions depend on the business activity, licensing authority and legal structure.
| Comparison | Mainland | Free Zone | Offshore |
|---|---|---|---|
| Main regulator | Dubai DET or relevant authority | Selected Free Zone authority (DMCC, IFZA, etc.) | Offshore registry (e.g. JAFZA Offshore, RAK ICC) |
| Foreign ownership | 100% for many activities, subject to conditions | Generally 100% | Generally 100% |
| UAE Mainland market | Direct access, subject to licence | Additional arrangements may be required (distributor, branch) | Normal Mainland trading is not permitted |
| International business | Yes | Yes | Holding and permitted international activities |
| Office requirement | Usually approved commercial premises (Ejari) | Flexible packages may be available (flexi-desk, office) | Registered address through the registry or agent |
| Residency visas | Available subject to eligibility | Available subject to package and eligibility | Generally not available |
| Typical purpose | Local UAE operations & public tenders | International business and specialised activities | Holding and investment |
| Setup cost | Depends on activity and premises (AED 15,000–35,000+) | Depends on Free Zone and package (AED 12,500–35,500+) | Depends on registry and structure |
Your business activity is one of the first details the licensing authority will ask for. It determines the licence category, permitted operations and any additional approvals.
For example, a company providing management advice may require a professional or consultancy licence. A business importing and selling products may need a commercial or trading licence. Manufacturing and industrial operations have separate industrial requirements.
Describe the specific products or services rather than selecting a broad activity simply because it appears convenient.
The licensing choice may differ depending on whether customers are in the UAE Mainland, outside the UAE or both.
Trading activities may involve customs code registration, clearance approvals, and bonded warehouse logistics.
Certain regulated services (legal, medical, audit, engineering) are subject to external regulator attestations.
Check whether the selected licensing authority permits combining multiple activities across commercial and professional groups under one licence.
Choosing the wrong activity can lead to additional approvals, licence amendments or restrictions on the work the company can undertake. It is better to settle this before submitting the incorporation application.
Foreign nationals, including Indian citizens, can establish businesses in Dubai, subject to the applicable company formation and licensing rules. The eligibility requirements depend on the selected jurisdiction, activity and legal structure.
Some business activities require additional approvals or may have specific ownership conditions. Eligibility should therefore be checked with the relevant licensing authority before committing to a particular structure.
The legal structure determines how a company is owned, managed and held responsible for its obligations. Common structures include:
An LLC is commonly used for Mainland businesses. It has a separate legal identity and generally limits shareholders' liability to their capital contribution, subject to applicable law.
An FZE is a Free Zone entity with a single shareholder. The shareholder may be an individual or a corporate entity, depending on the authority's rules.
This structure is generally used where there are two or more shareholders. The exact permitted shareholder count and legal form depend on the Free Zone authority.
A sole establishment is owned by one individual. Unlike a limited liability structure, the owner may have personal liability for the business's obligations.
A civil company is used for certain professional activities, such as consultancy and other licensed professional services. The permitted ownership and liability arrangements depend on the activity and licensing rules.
A branch is an extension of an existing parent company. It allows the parent company to establish a presence in Dubai without incorporating a completely separate subsidiary. A branch generally carries out activities permitted to the parent company.
A subsidiary is a separate legal entity owned wholly or partly by a parent company. It has its own incorporation documents, accounts and compliance responsibilities.
An Indian company considering expansion into Dubai may compare a subsidiary with a branch before deciding how to establish its overseas presence, taking into account tax liabilities, FEMA compliance, and operational independence.
Yes. In many cases, Indian citizens can complete a significant part of the company formation process without travelling to Dubai.
Depending on the selected authority and company structure, the process may involve submitting passport copies, shareholder details, application forms and corporate documents electronically.
However, remote incorporation does not mean every step can always be completed from India. The licensing authority, bank or immigration department may require:
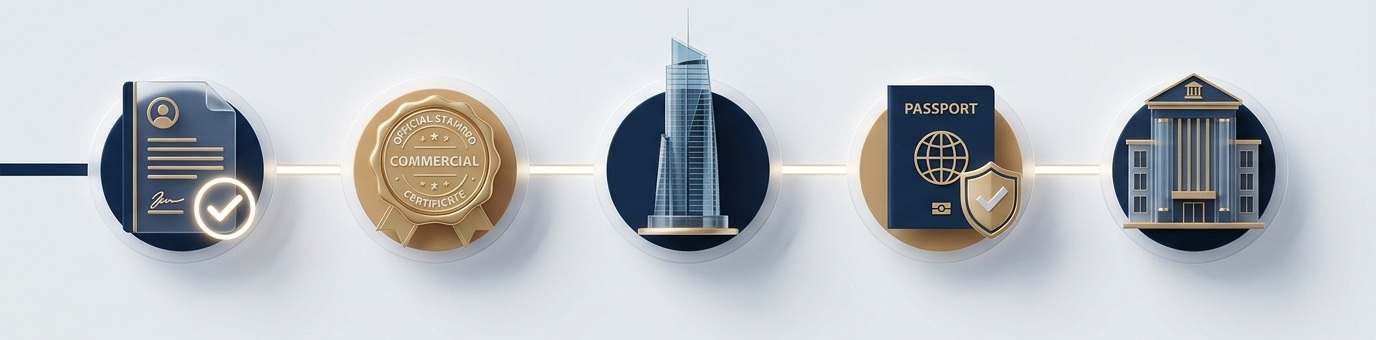
The company registration process varies between Mainland and Free Zone authorities. However, most applications involve the following 10 steps managed end-to-end:
Identify the activities the company intends to undertake. Check whether any special approval or professional qualification is required.
Decide whether a Mainland, Free Zone or Offshore structure is appropriate. Consider market access, ownership, office requirements, visas and tax implications.
Choose the legal form based on the number of shareholders, ownership arrangement and business requirements (LLC, FZE, FZC, Branch, or Subsidiary).
Submit the proposed company name for approval. The name must comply with the applicable UAE naming rules and cannot contain prohibited or misleading terms.
Apply for initial approval from the relevant licensing authority. Certain activities may require additional approvals from sector-specific regulators.
Provide shareholder, director and beneficial ownership details. The authority may request identity documents, ownership charts, source-of-funds information and other KYC records.
Prepare the Memorandum of Association (MOA), Articles of Association (AOA), board resolutions and other documents required for the selected structure.
Complete the office or workspace requirement. Mainland companies generally need approved commercial premises (Ejari), while some Free Zones offer flexi-desk and shared-office packages.
Submit the final documents, pay the applicable fees and receive the trade licence and certificate of incorporation.
Depending on the company, this may include immigration and establishment files, corporate bank account opening, tax registration (Corporate Tax & VAT), customs registration and activity-specific permits.
The documents depend on whether the shareholders are individuals or existing companies. The licensing authority may request additional records based on the activity and ownership structure.
Legalisation & Attestation: Corporate documents issued outside the UAE may need notarisation, attestation or legalisation (e.g. from the Ministry of External Affairs and the UAE Embassy in India). The exact requirements should be confirmed with the selected authority before documents are prepared.
The cost of setting up a company in Dubai depends on the jurisdiction, activity, legal structure, office arrangement and number of visas required. There is no single registration fee that applies to every business.
| Company Type | Indicative Setup Cost |
|---|---|
| Mainland company | AED 15,000 – 35,000+ |
| Free Zone company | AED 12,500 – 35,500+ |
| Offshore company | Depends on the registry and structure |
*The figures above are indicative planning estimates, not official fee quotations. The actual amount may be higher where the business needs additional external approvals, larger physical premises, specialised licences or several employee visas.
The main cost components may include:
The timeline depends on the selected jurisdiction, activity and completeness of the documents. A straightforward application with a standard activity may be processed relatively quickly (often within 3 to 7 working days in Free Zones, or 1 to 2 weeks in Mainland). However, activities requiring external approvals, corporate shareholder documents or additional verification can take longer.
Avoid expensive licensing errors, banking rejections, or cross-border FEMA/tax pitfalls. Get tailored advice on Mainland, Free Zone, and Offshore jurisdictions.
Indian residents planning to invest in a Dubai company must consider the Foreign Exchange Management Act (FEMA) and the Overseas Investment (OI) framework.
The Foreign Exchange Management (Overseas Investment) Rules, 2022 and related RBI regulations govern overseas investment by persons resident in India. The route and reporting requirements depend on who is investing, the nature of the investment and the proposed foreign entity.
ODI generally involves acquiring an ownership interest in a foreign entity with a lasting business interest or control, subject to the applicable definitions and rules. An Indian company investing in a Dubai subsidiary may need to follow the ODI route, including the applicable financial commitment limits (up to 400% of net worth), designated Authorised Dealer (AD) bank process, Unique Identification Number (UIN) issuance, and statutory reporting requirements.
Resident individuals may also make permitted overseas investments, subject to the Overseas Investment framework and the applicable Liberalised Remittance Scheme (LRS) limits ($250,000 per financial year) and conditions. The rules are not identical for individuals and Indian companies. The proposed shareholding, control, nature of the Dubai entity and source of funds should be reviewed before money is remitted.
Depending on the transaction, compliance may include:
Advisory Rule: A Dubai company should not be incorporated first and the Indian FEMA position considered only afterwards. Planning the investment route in advance can help avoid reporting and remittance issues.
Incorporating a company in Dubai does not automatically make its Indian shareholders non-residents for Indian tax purposes. The tax treatment depends on the residential status of the individual, the ownership arrangement, the source of income and where the company is actually managed.
Indian residents with overseas investments should review both UAE tax obligations and their reporting responsibilities in India.
An individual's tax residency in India is determined under the Income-tax Act, based on applicable residential status tests, including the number of days spent in India and other relevant conditions. A person may be required to pay tax in India on global income depending on their status. Therefore, an Indian resident who owns shares in a Dubai company should not assume that income earned outside India is automatically outside the Indian tax net (ROR vs RNOR vs Non-Resident).
The Place of Effective Management (POEM) concept determines the tax residency of a foreign company under Indian tax law. If the key management and commercial decisions of a foreign company are effectively made in India, the company may be treated as an Indian tax resident. Registering a company in Dubai while controlling its operations and making major decisions from India can create severe POEM exposure.
India and the UAE have a Double Taxation Avoidance Agreement (DTAA) to address situations where income may be taxable in both countries. The treaty provides rules for different categories of income and offers double taxation relief. However, treaty benefits are not automatic: Tax Residency Certificates (TRC), Form 10F, and beneficial ownership documentation are strictly required.
Indian residents falling within the applicable reporting category must disclose foreign assets and income in their income tax returns under Schedule FA. This covers foreign bank accounts, equity interests in foreign entities, and overseas immovable property. Failure to report foreign assets where required can trigger severe penalties under the Black Money Act.
Company incorporation is only the first stage. A Dubai company must continue to meet its tax, accounting and regulatory obligations after receiving its licence. The requirements vary by jurisdiction, business activity and company structure.
The UAE Corporate Tax regime applies to companies and other taxable persons within its scope, including companies established in Free Zones. The general Corporate Tax rates are:
The calculation is based on taxable income under UAE Corporate Tax rules, not simply the gross turnover or cash received. Companies must register with the Federal Tax Authority (FTA), maintain accounting records, prepare financial statements and submit Corporate Tax returns within 9 months of the financial year-end.
A Free Zone company may qualify for a 0% Corporate Tax rate on qualifying income if it meets the conditions prescribed under UAE law:
Income that does not qualify may be subject to the standard 9% rate. A company should review its revenue streams, customer locations, activities and related-party transactions before relying on the Free Zone tax benefit.
The standard VAT rate in the UAE is 5%.
Transfer pricing rules apply to transactions between related parties and connected persons.
If an Indian parent provides management services, loans, intellectual property or goods to its Dubai subsidiary, pricing must follow the arm's-length principle. Companies must maintain supporting records, benchmarking studies, and local/master transfer pricing files where applicable.
Dubai companies must maintain proper accounting records reflecting actual business transactions:
Audit requirements depend on the legal structure, licensing authority and applicable regulations.
Certain Free Zones (e.g. DMCC, JAFZA) require companies to submit audited financial statements annually. A Qualifying Free Zone Person (QFZP) must also maintain audited financial statements under the Corporate Tax framework. Mainland companies have statutory audit obligations depending on commercial law.
UAE companies are required to identify and maintain information about their Ultimate Beneficial Owners (UBOs). A UBO is generally the natural person who ultimately owns or controls 25% or more of the company, directly or indirectly.
Companies must maintain a beneficial ownership register and submit details to the licensing authority:
AML obligations differ by business activity. Regulated businesses and Designated Non-Financial Businesses and Professions (DNFBPs)—such as real estate brokers, corporate service providers, dealers in precious metals/stones, and accountants—have additional customer due diligence, reporting and goAML filing obligations. Furthermore, banks conduct independent KYC checks before opening corporate accounts or processing transactions.
Business owners may be eligible to apply for UAE residence visas through an appropriately licensed company, subject to immigration rules and the company's eligibility. The number of visas available depends on the jurisdiction, office arrangement, licence package and physical workspace size.
Issued to company shareholders and partners, typically valid for 2 or 3 years renewable, providing official UAE residency status.
Allocated under the company's visa quota package, enabling the employment and relocation of international talent.
Eligible investors and employees can sponsor spouses, children, and parents once their own residence visa is stamped.
The process involves opening an establishment/immigration file, obtaining an entry permit, completing a medical fitness test, biometric scanning for the Emirates ID, and residence visa stamping. Note that an Offshore company generally does not provide the same visa facilities as an operating Mainland or Free Zone company.
A company must continue to meet its licensing, tax and regulatory responsibilities after incorporation. The compliance calendar depends on the jurisdiction, activity and legal structure. Common recurring requirements include:
Setting up a company in Dubai involves decisions that can affect its operations and tax position for years. Choosing a jurisdiction only on the basis of the initial licence fee may create problems later if the company needs to change its activity, access the UAE Mainland market or meet additional compliance requirements.
Vidhu Duggal & Company (VDC) assists entrepreneurs, investors and businesses with the financial, tax and regulatory aspects of establishing a presence in Dubai:
Whether you are an Indian entrepreneur planning your first overseas venture or an established business looking to expand into the UAE, our team can help you understand the requirements before you begin the registration process.
Contact Vidhu Duggal & Company to discuss your business activity, proposed structure and compliance requirements.
Expanding across international borders? Explore our complementary regulatory and tax advisory services:
End-to-end guidance for UAE & international firms setting up wholly-owned subsidiaries, branch offices, or liaison offices in India.
Cross-border intercompany transaction structuring, BEPS compliance, and India-UAE double taxation avoidance treaties.
Specialized advisory for offshore banking units, family offices, and foreign funds establishing in India's premier tax-neutral financial centre.
Outsourced CFO leadership, MIS reporting, multi-currency bookkeeping, and corporate tax compliance across UAE and India.
Free Consultation
Our experts are here to guide you every step of the way.
Clear, authoritative answers to the most common queries regarding company formation, costs, taxes, visas, and banking in the UAE.
Vidhu Duggal and Company (‘VDC’) is a Delhi-based Chartered Accountancy firm with a strong staff of competent and proficient Chartered Accountants that are capable of handling all aspects of the financial services industry.
Vidhu Duggal & Company © | All Rights Reserved
Technical Partner -