India’s GIFT City The New Global Financial Hub
GIFT City stands for Gujarat International Finance Tec-City, a financial and IT services township near Gandhinagar, Gujarat. Within it sits India's first International Financial Services Centre (IFSC), a notified zone where entities can run financial services business in foreign currency, largely outside the domestic regulatory perimeter.
GIFT City is the geography. GIFT IFSC is the regulatory zone within it. Only entities incorporated within the IFSC get the foreign-currency operating model, tax incentives and single regulator that make GIFT City attractive.
That regulator is the International Financial Services Centres Authority (IFSCA), set up in 2020 to replace the earlier split oversight across RBI, SEBI, IRDAI and PFRDA. Businesses use the IFSC framework because it lets them run genuinely international operations while staying anchored in India.
Free Consultation
The reasons vary by business, so it's worth knowing which ones actually apply to you.
IFSC entities operate as a deemed foreign jurisdiction for most transactional purposes, letting you transact in foreign currency and access exchanges like NSE IFSC and India INX without routing through a domestic entity.
GIFT IFSC units qualify for a multi-year profit-linked deduction under Section 80LA, along with GST and stamp duty relief on qualifying transactions. The specifics depend on your entity type and licensed activity.
One regulator instead of three or four means one application process and one point of contact for ongoing compliance.
Most IFSC entities transact and book revenue in foreign currency by default, removing conversion friction for businesses with dollar- or euro-denominated clients and costs.
IFSC entities are treated as non-resident for many FEMA purposes, making it easier to transact with persons resident outside India.
GIFT City now has real depth: fund administrators, custodians, banking units and legal and compliance providers, which lowers the operational lift of setting up.
Grade-A office space, data centre capacity and connectivity built for financial services, without needing to set up in Mumbai or offshore.
Not every financial activity is automatically permitted. Eligibility depends on the applicable IFSCA regulations and, in most cases, obtaining a registration or licence before operating.
Foreign and Indian banks can set up IFSC Banking Units (IBUs) for wholesale banking in foreign currency.
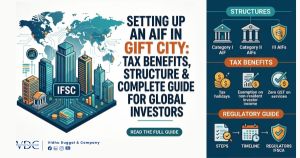
Category I, II and III AIFs, venture capital schemes and portfolio management businesses can be set up under the IFSCA Fund Management Regulations.
Exchanges, clearing corporations, depositories and intermediaries operate under IFSCA's capital markets regulations.
International Financial Services Centre Insurance Offices (IIOs) can write direct insurance and reinsurance business.
A dedicated framework, including a regulatory sandbox, supports payments, regtech, insurtech and blockchain-based products.
GIFT IFSC has become an alternative to Ireland and Singapore for aircraft lessors, backed by a dedicated tax and regulatory framework.
A newer but growing category, following a similar model to aircraft leasing.
Multinational groups increasingly set up Global Capability Centers in GIFT IFSC to deliver finance, risk and technology functions to their global group.
Corporate treasury centres managing group financing, cash pooling and hedging in foreign currency fit naturally into the IFSC structure.
IFSCA continues to expand the permitted list, including sustainable finance and bullion exchange participants. If your activity isn't listed above, it's worth a proper eligibility check before committing to a structure.
GIFT City accommodates multiple legal structures depending on business scope and capital requirements:
Start with the business activity, since it drives the applicable regulatory requirements, including any minimum capital or net-worth thresholds.
Ownership matters too. A wholly-owned subsidiary of a foreign parent may suit a branch structure, while outside investors are usually better served by a private limited company.
Capital requirements, tax considerations and liability tend to move together. A private limited company ring-fences liability and is usually more tax-efficient for reinvested profits, while an LLP suits a smaller, founder-led business.
Finally, weigh your operational objectives and long-term plans. An entity meant to raise institutional capital or list should almost always be a company from day one.
| Structure | Best Suited For | Liability | Typical Use Case in GIFT IFSC |
|---|---|---|---|
| Private Limited Company | Operating businesses raising capital | Limited to the company | Fund managers, fintechs, insurers, banks |
| LLP | Smaller, founder-led professional activity | Limited, with partner flexibility | Advisory and support service providers |
| Branch of foreign/Indian entity | Existing entities extending operations | Liability sits with parent | IBUs, IIOs, group treasury extensions |
| Trust | Pooled investment vehicles | Limited to trust corpus | AIFs, fund structures |
Our GIFT City Entity Setup Services follow a clear sequence designed to navigate regulatory checkpoints smoothly:
We start by understanding the business objectives, confirming regulatory eligibility, and selecting the optimal entity structure.
We identify the applicable IFSCA regulatory framework, draft the comprehensive business plan, and evaluate office and infrastructure requirements.
With the groundwork completed, we execute company/LLP incorporation, prepare and submit the IFSCA registration application, and liaise with authorities through approvals.
Once approved, we handle post-approval tax registrations, bank accounts, and regulatory filings before operations commence, setting up your ongoing compliance calendar from day one.
IFSCA is the regulatory authority throughout this process. A strong application includes a clear business plan and detailed promoter and director information, including financial standing and relevant experience.
Where minimum capital or net-worth requirements apply, they need to be demonstrated upfront. Regulatory review typically involves one or more rounds of clarification. Some activities receive an in-principle approval before final registration, followed by post-approval requirements such as commencing operations within a set period.
There is no single universal approval timeline. A fund management registration and a full banking unit application move at very different speeds.
Tax law changes regularly, so any rate or section reference here should be verified against current law before relying on it.
GIFT IFSC units are eligible for a profit-linked deduction under Section 80LA for a defined block of years. Corporate tax applies at standard rates on income outside that deduction and Minimum Alternate Tax (MAT) treatment for IFSC units has historically been more favourable than the standard regime.
Withholding tax on payments to and from IFSC units, including interest paid to non-residents by banking units, often benefits from concessional rates. On indirect taxes, GST benefits apply to specified services, several supplies qualify for zero-rating as exports and customs benefits extend to goods brought in for authorised operations.
Tax treaty considerations matter given the volume of cross-border dealings and transfer pricing applies fully to related-party transactions, alongside IFSCA's own reporting expectations.
GIFT IFSC entities are treated as person resident outside India for many FEMA purposes, changing how foreign investment, capital flows and repatriation work compared to a standard subsidiary.
Foreign currency transactions are the default mode of operation and repatriation typically faces fewer frictions than for a domestic company, though the route depends on the entity's activity and structure.
RBI considerations still apply in specific areas, such as banking units operating under RBI directions alongside IFSCA regulation. FDI reporting obligations continue to apply where relevant and getting resident and non-resident treatment right for each counterparty is a genuinely technical part of ongoing compliance.
Operating an IFSC entity requires adhering to coordinated compliance streams:
There is no single cost figure. It depends on entity type and regulated activity:
Timelines depend on entity type, business activity, documentation readiness, capital requirements, the pace of IFSCA's review and how many rounds of clarification the application goes through.
Some advisors quote a four-to-eight-week range for well-prepared applications in simpler categories, which is a reasonable benchmark for something like a fund management registration. It isn't a promise and it isn't the right expectation for a banking or insurance application, where review typically runs longer.
Understanding the core operational differences helps determine whether an IFSC entity is the right vehicle:
| Factor | GIFT City IFSC | Traditional Indian Setup |
|---|---|---|
| Regulatory Framework | Single regulator (IFSCA) | Multiple regulators depending on activity |
| Permitted Business Activities | Defined list of financial and ancillary services | Broad, sector-agnostic |
| Tax Incentives | Section 80LA deduction, GST/customs relief | Standard domestic tax rates |
| Currency of Operation | Predominantly foreign currency | Indian rupee |
| FEMA / Residency Treatment | Largely person resident outside India | Standard resident entity treatment |
| Compliance Layers | IFSCA plus Companies Act, tax and SEZ | Companies Act and tax only |
| Best Suited For | Cross-border financial services, treasury, funds, GCCs | Domestic-facing businesses |
Key Takeaway: GIFT City suits businesses with predominantly international revenue and clients. A standard domestic setup is usually simpler for India-facing businesses.
Our advisory approach is tailored to the specific industry framework:
The work centres on fund structuring and getting the AIF or PMS category right under IFSCA Fund Management Regulations.
Navigating the regulatory sandbox, sandbox testing, and direct licensing pathways for cross-border innovation.
Assisting domestic and foreign banks with IBU setup and the parallel RBI-IFSCA dual compliance layer.
End-to-end IIO registration, underwriting compliance, capital adequacy, and statutory reporting frameworks.
Registration and operational compliance for intermediaries, broker-dealers, and clearing members.
Specialised, asset-financing focused structuring capitalizing on competitive lease regimes.
A tailored blend of corporate entity structuring, cross-border transfer pricing, and FEMA advisory for multinational captive centres.
We offer full-lifecycle support covering every phase of your IFSC operations:
Free Consultation
Our experts are here to guide you every step of the way.
GIFT City is the township, GIFT IFSC is the notified financial centre within it, regulated by IFSCA, where eligible entities can operate largely in foreign currency.
Banking units, fund managers and AIFs, capital market intermediaries, insurers, fintech firms, aircraft and ship lessors, GCCs, treasury centres and other IFSCA-permitted services.
Access to global markets, a single regulator, tax incentives, foreign-currency operations and a maturing financial services ecosystem.
Private limited company, LLP, branch structures, trusts for fund vehicles and other permitted structures depending on activity.
Confirming eligibility, choosing the structure, identifying the applicable framework, incorporation, IFSCA application and approval, registrations and ongoing compliance.
A Section 80LA profit-linked deduction, concessional withholding tax and MAT treatment, GST relief on specified services and customs benefits, subject to conditions.
IFSCA is the unified regulator covering banking, capital markets, insurance, fund management and other financial services.
IFSC entities are generally treated as persons resident outside India for FEMA purposes, though RBI oversight still applies in areas like banking units.
Cost depends on entity type and activity, covering incorporation, professional fees, IFSCA application costs, office costs and capital requirements.
Simpler categories can move in a matter of weeks, capital-intensive categories like banking and insurance typically take longer.
GST applies, but specified services often qualify for relief or zero-rating as exports.
IFSCA reporting, Companies Act filings, tax and GST compliance, FEMA/RBI reporting, transfer pricing documentation, accounting and audit and SEZ obligations.
Yes, the framework is designed to accommodate foreign parents alongside Indian promoters.
Base it on business activity, regulatory thresholds, ownership plans, capital requirements, tax position, liability preference and long-term objectives.
We manage the full lifecycle, from feasibility and structuring through IFSCA registration, tax and FEMA advisory, transfer pricing, accounting and ongoing compliance. Contact us at www.vidhuduggalandco.com
Leverage India's global financial hub with expert guidance.
Vidhu Duggal and Company (‘VDC’) is a Delhi-based Chartered Accountancy firm with a strong staff of competent and proficient Chartered Accountants that are capable of handling all aspects of the financial services industry.
Vidhu Duggal & Company © | All Rights Reserved
Technical Partner -